Military Homebuying
Buying a Home Near Robins Air Force Base With a VA Loan
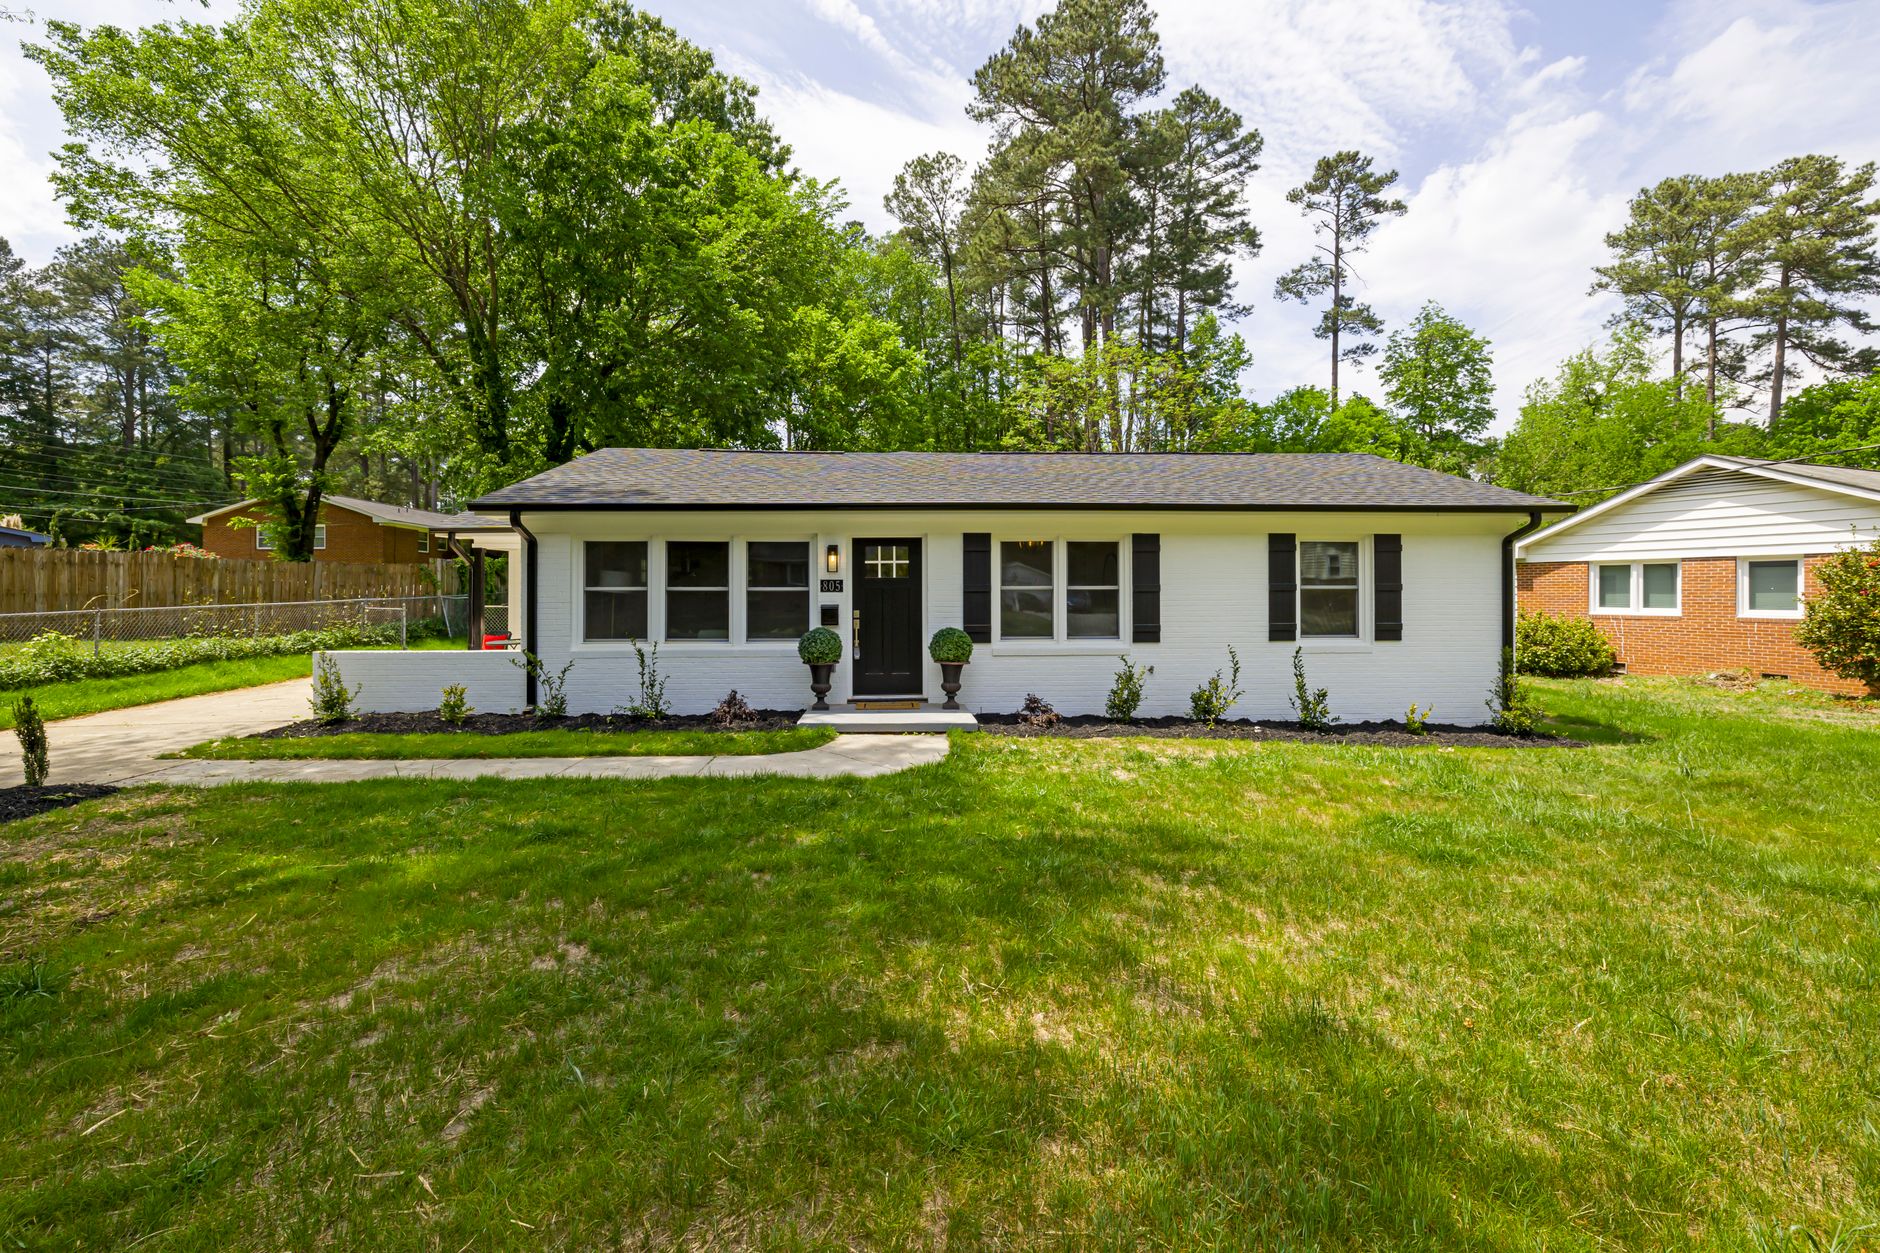
Buying a home near Robins Air Force Base, GA, with a VA loan starts with two practical questions: Which gate will you use, and what will your lender need before closing? The loan benefit can make the purchase possible without a down payment, but it does not make every house or every commute a good fit. I help military and veteran buyers sort out both sides of that decision before they commit to an address.
Choose a house by the gate you will actually use
“Near Robins” covers several different daily routines. Homes in Warner Robins may put you closer to Watson Boulevard or Russell Parkway; Bonaire and Kathleen buyers often consider the Russell Parkway approach, while Perry adds a longer drive from farther south. I have handled properties at 917 Abingdon Cove in Bonaire and 404 Childers Drive in Warner Robins, and I would never treat those two addresses as interchangeable just because both serve the base area.
Robins’ published gate information, checked for this November 2026 guide, lists the Watson gate as open around the clock, the Russell Parkway gate as open daily from 5 a.m. to 10 p.m., and the Green Street gate as open on weekdays except holidays from 5 a.m. to 6 p.m. If you work nights or unpredictable shifts, a route that depends on a limited-hours gate deserves a second look. Gate schedules can change, so confirm them with the base and drive your likely route at your actual reporting time before making an offer.
For school-age children, check the specific property address through Houston County Schools’ zoning lookup. A Bonaire or Warner Robins mailing address alone does not tell you which school serves the house. The district also describes a military school-transfer option tied to qualifying military housing; do not assume that buying a private off-base home lets you select any school. I can help narrow the search, but the district should confirm an address and any transfer eligibility.
Get the VA loan details settled before touring
For a VA home loan in Warner Robins, your first call should be to a lender who regularly handles VA purchases. Ask the lender to obtain or review your Certificate of Eligibility, confirm any remaining entitlement if you already have a VA loan, and explain how your orders, income and planned occupancy affect the application. VA backs the loan; a private lender makes it and evaluates whether you qualify for the amount you want to borrow.
Then compare Loan Estimates rather than assuming every VA offer has the same rate or fees. VA says a purchase loan may require no down payment when the price does not exceed the appraised value, and it does not require private mortgage insurance. That still leaves an appraisal, insurance, closing costs and the possibility of a funding fee. Some borrowers qualify for a funding-fee exemption, including certain people receiving VA compensation for a service-connected disability; have your lender verify your status instead of budgeting from a guess.
current homes in the area only after you know the payment and cash-to-close range you can live with.
Inspect for the house you are buying
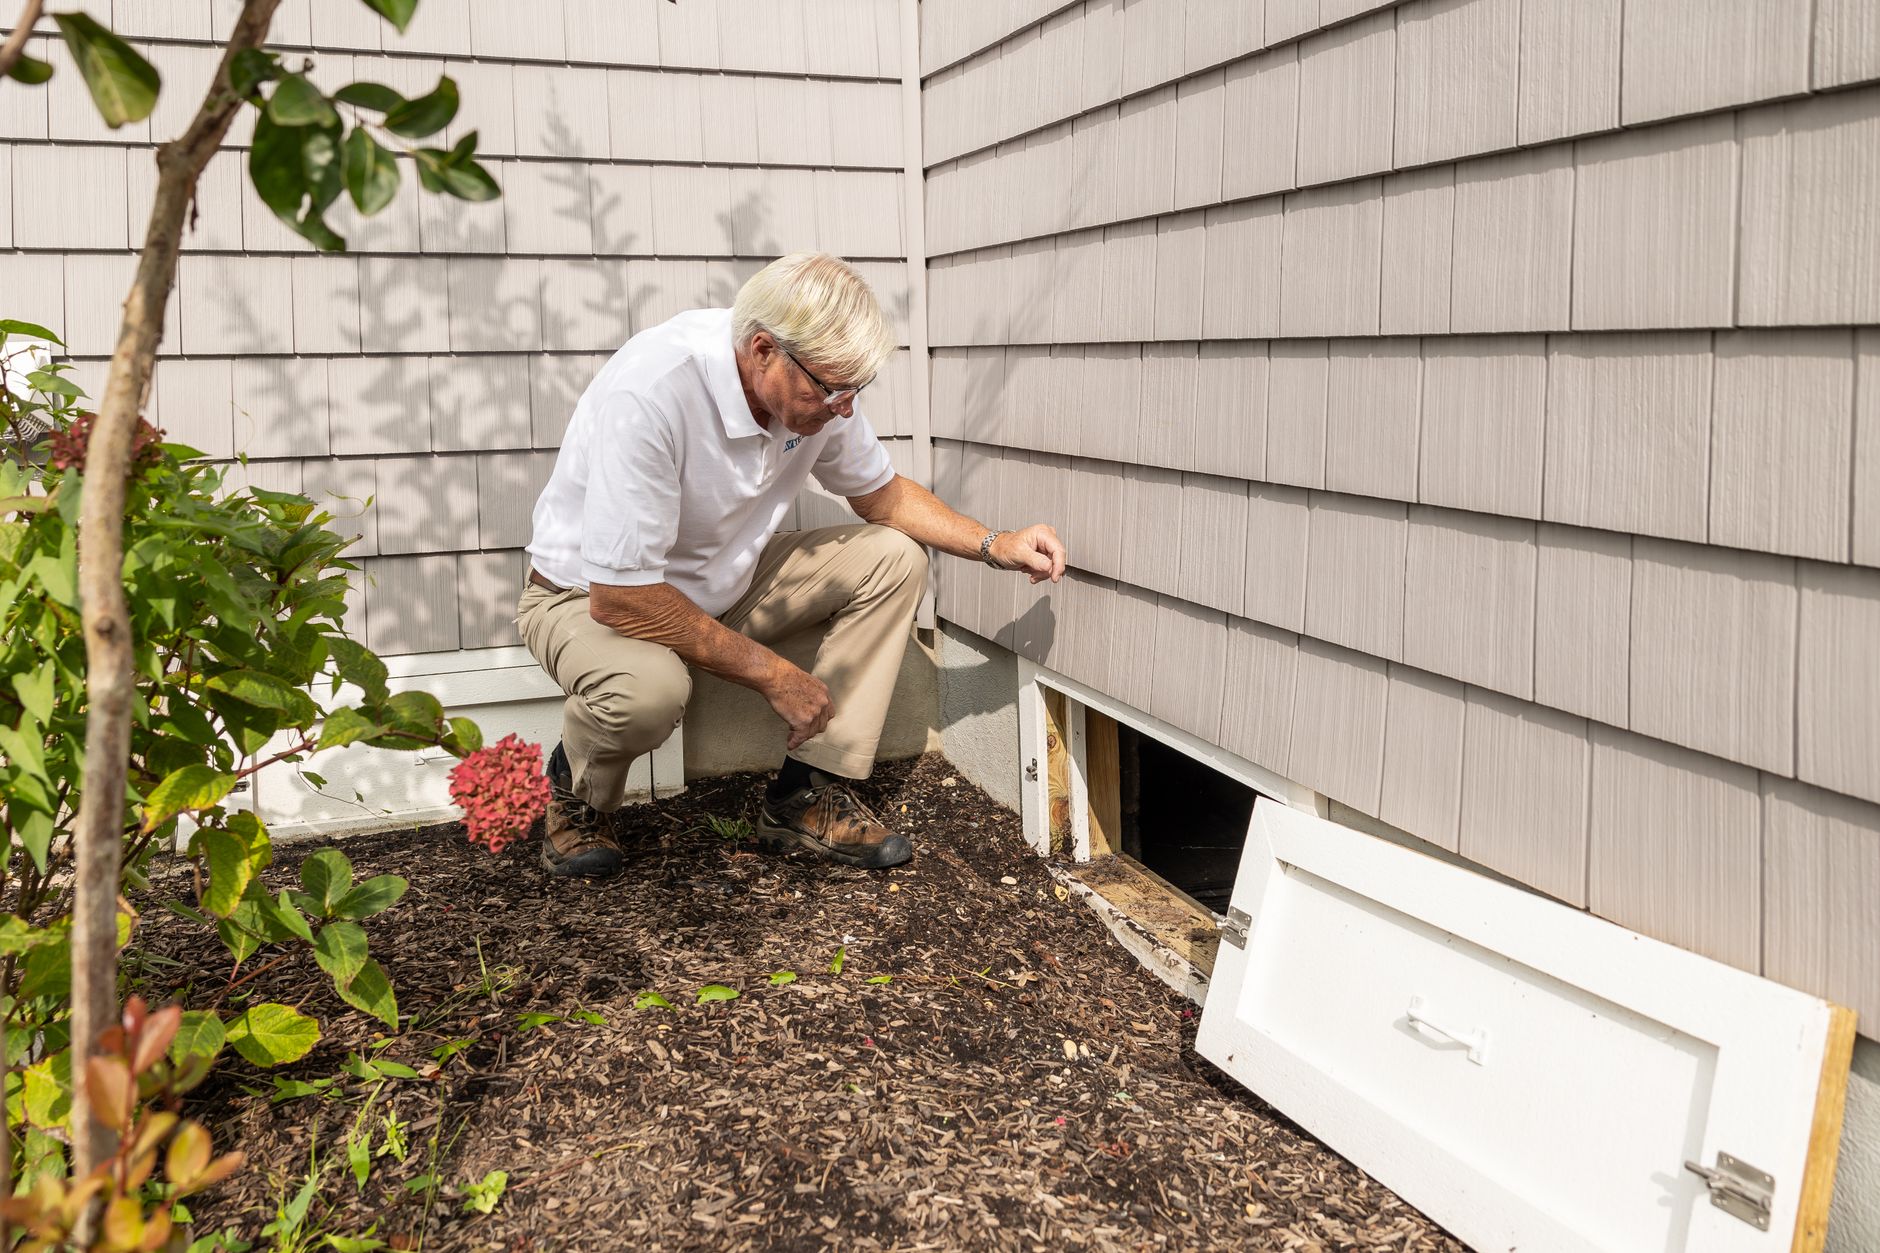
The VA appraisal addresses value and basic property requirements. It is not a full home inspection. Around Middle Georgia, I would want an inspector to pay close attention to roof condition, drainage and the crawl space where applicable, along with the heating and cooling system. Those are sensible checks for a home you will own, regardless of loan type. If there are signs of wood damage or moisture, ask qualified professionals what additional evaluation is appropriate.
Once the house is under contract, your lender arranges the VA appraisal. If it identifies required repairs, find out who will do the work and whether it can be finished before your scheduled closing. A tight relocation calendar makes that conversation more important. A house with a repair issue is not automatically out of reach, but you need a workable plan that the seller, lender and contract deadlines support.
If the VA value comes in below the contract price, VA describes several possible responses: supply relevant sales data through the lender for reconsideration, renegotiate with the seller, or cover the difference yourself if you choose to proceed. The VA escape clause addresses a low VA value; it does not substitute for a separate inspection contingency. I want that distinction clear before my buyers sign, especially when an inspection period is short.
Build an offer that accounts for cash and timing
No down payment does not mean no money due during the purchase. Budget for earnest money, inspection costs and the appraisal, then ask the lender for a written estimate of closing costs and prepaid items. According to VA’s closing-cost guidance updated in October 2026, the VA funding fee may be financed into a purchase loan, but other purchase closing costs cannot simply be rolled into it.
protecting your cash when buying a home.
An offer near Robins also needs dates that make sense for a military move. Tell me when you must report, whether you can attend an inspection, and whether temporary housing gives you any flexibility. I will help set realistic contract deadlines and coordinate with the lender; I will not promise that a seller can repair an issue or that underwriting can finish on your preferred day.
Make the final decision with both the move and the loan in view
I work with military families, veterans and relocating buyers across Warner Robins, Bonaire, Kathleen and Perry. My job is to help you compare actual houses and routes, ask the right questions early, and negotiate with your timeline in mind. If you are receiving orders to Robins or already live nearby, we can build a search around your gate, your preferred school-zone addresses and the homes your lender says fit your financing.
This is general information, not legal or financial advice. Ask your lender about loan terms and a qualified attorney about contract questions specific to your purchase.
Sources
- Robins Air Force Base, Driving on Base: Gate Hours, Rules and Driving Directions (accessed November 2026)
- Houston County Schools, Zoning and address lookup (accessed November 2026)
- U.S. Department of Veterans Affairs, Purchase Loan (updated January 2026)
- U.S. Department of Veterans Affairs, Buying a Home With a VA-Backed Loan (updated January 2026)
- U.S. Department of Veterans Affairs, VA Funding Fee and Loan Closing Costs (updated October 2026)
Frequently asked questions
- Which gate should I use when looking at homes near Robins Air Force Base?
- Start with the gate that fits your duty hours. Robins lists Watson as open around the clock; Russell Parkway and Green Street have limited hours. Confirm the current schedule with the base and test the drive from any home you are seriously considering.
- Can I buy a home in Bonaire or Kathleen with a VA loan?
- A VA-backed purchase loan is not restricted to Warner Robins. You can consider eligible properties in Bonaire, Kathleen, Perry and elsewhere, subject to your lender’s approval, the home’s appraisal and property requirements, and the VA occupancy requirement.
- Will a VA appraisal replace a home inspection on a Houston County house?
- No. The VA appraisal looks at value and basic property requirements; a separate inspection can examine the roof, crawl space, HVAC and other systems in greater depth. VA strongly recommends an inspection.
- Does a VA loan mean I need no cash to close near Robins AFB?
- No. A qualifying VA purchase may require no down payment, but you could still pay for an inspection, appraisal, insurance and closing costs. Ask your lender for a Loan Estimate and confirm whether you owe a VA funding fee or qualify for an exemption.